Your PBM Is Your Health Plan’s Blind Spot

Kirk Conole • October 26, 2026

Cut pharmacy costs 30% and you cut total plan costs about 10%.


Here’s why we recommend auditing the most conflicted, most overpaid, least examined entity in your benefits plan:


Pharmacy audits regularly uncover PBMs charging plans $80–$100 for drugs they paid the pharmacy $15–$25 for. Your report shows only what you paid, and the contract lets the PBM keep the difference.


Keep your broker. Keep your PBM.


Self-insured with 100 or more employees?


Get DCI’s Free Pharmacy Savings Forecast

Who sets your price?

NADAC is a public benchmark of what pharmacies pay for drugs. Your PBM bills from its own price list.


Express Scripts’ parent owns Quallent, a generic drug label. Researchers at 46brooklyn found its list prices averaged about 38 times wholesale cost, and one generic launched roughly 7,000% above the cheapest competitor.


A discount off a price your PBM sets is no discount.


✔ Is your guarantee a discount off list price? Then ask who set the list price.

An average discount hides overpriced drugs.

A “generic effective rate” averages discounts across all generics. Your PBM meets the guarantee while overcharging for the drugs your employees take most. This makes your big, promoted discount irrelevant.


Pricing guarantees often cover less than three-quarters of plan spending because specialty drugs, compounds, vaccines and diabetic supplies are often excluded.


✔ Does your contract price your top 25 generics by name?

“100% of rebates,” after their cut.

Manufacturer rebates often pass through an aggregator owned by the PBM’s parent, which takes its cut first. Admin fees and inflation payments fall outside the rebate definition.


You receive 100% of what remains.


Meeting your rebate guarantee proves the PBM paid the promised minimum—not that it passed through everything it collected.


✔ Does your contract cover every manufacturer payment, whichever affiliate receives it?

Their pharmacy, their profit.

Specialty classifications, mail-order incentives and automatic refills steer prescriptions to pharmacies the PBM owns.


The FTC found those pharmacies generated $7.3 billion above estimated acquisition cost on specialty generics from 2017 to 2022.


Measure mail-order savings by net cost, claim by claim, not the discount. Automatic fills members never requested add to your bill.


✔ How much of your spending goes to PBM-owned pharmacies?

Add up every fee.

The admin fee leaves out clinical program, reporting, network and implementation fees. Your plan often pays a higher dispensing fee than the pharmacy receives, and the PBM keeps that difference too.


✔ Does your PBM disclose every fee in one total?

Who keeps recovered overpayments?

Your PBM recovers overpayments from pharmacies on claims your plan funded. Your contract determines whether that money comes back to you.


✔ Does your contract return every recovery to your plan?

The PBM grades its own work.

Many contracts let the PBM approve your auditor, select the claims and exclude rebate records.


✔ Can you choose your auditor and give them access to all claims and rebate records?

DCI checks your contract against your claims.

DCI’s pharmacists review your agreement and 12 months of claims. You see what your plan paid, what the pharmacy received and what the PBM kept, along with the savings amount and the contract changes needed.

Didn’t Congress fix this?

The new federal rebate requirements begin January 1, 2029, for calendar-year plans. Your contract renews before then.


When does your contract renew automatically—and what’s the deadline to stop it?

Get DCI’s Free Pharmacy Savings Forecast Before Your Next Renewal

Let's Talk

At DCI Solutions, we help companies take a more strategic approach to savings.


If you’d like to learn more about how DCI can help your company, we’re happy to have a conversation.


Please feel free to contact us here: info@dcisolutions.net | 760-809-8734  or set up a meeting here .
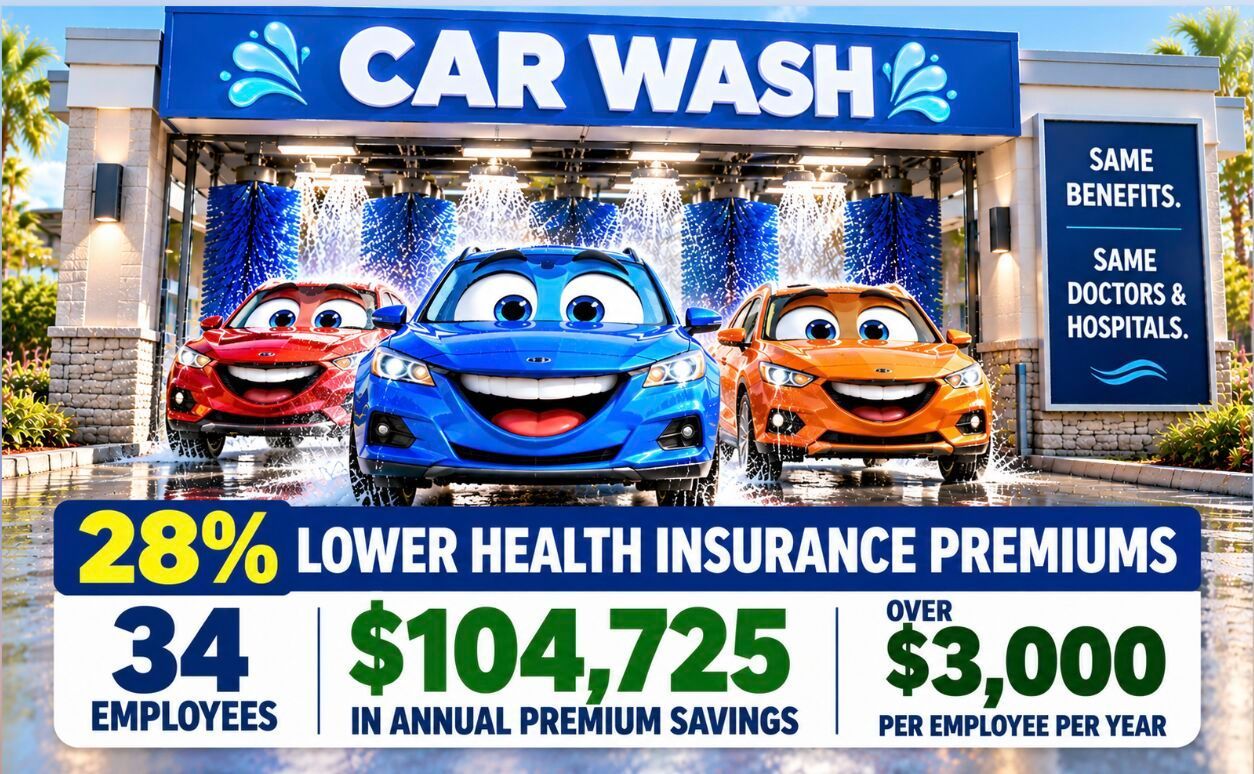
Car wash ad with cartoon cars, advertising 28% lower health insurance premiums and $104,725 savings per employee.
By Kirk Conole • October 21, 2026
Discover how a car wash chain saved $104,725 annually on employee health insurance without changing benefits, doctors, or hospitals.
By Kirk Conole • August 27, 2026
Every year, companies renew millions of dollars in Property & Casualty insurance with essentially the same process: The broker presents the renewal. Executives review it. Maybe there’s a discussion about rates or coverage changes. Then the company signs. Why? Often, it comes down to two assumptions: “Our broker does a good enough job.” Or: “It’s too messy to look into right now. We’ll just have to trust our broker.” But there’s an important question between trusting your broker and automatically renewing: How certain are you that your broker eliminated every meaningful coverage gap and left $0 on the table?  If the answer is anything less than “absolutely certain,” an independent review may be worth considering.
By Kirk Conole • August 13, 2026
Many companies assume the only way to find out whether they're overpaying for Property & Casualty insurance is to shop the account. That usually means involving the broker, approaching carriers and potentially disrupting the market. But there is another option: independent, confidential verification. A company can evaluate its current insurance program to determine where it may be overpaying, where coverage gaps may exist and which appropriate markets may have been overlooked, without immediately alerting the incumbent broker or approaching carriers. That means no awkward broker conversation, no market disruption and no commitment to make a change.
By Kirk Conole • August 5, 2026
When was the last time you called your own company to see what a prospective customer experiences? You might be surprised. While websites, chatbots, and AI assistants have transformed how businesses communicate, one fact hasn't changed: many buyers, especially executives and decision-makers over 60, still prefer to pick up the phone when they're ready to make a purchase. That's often the moment of highest buying intent. So what happens when they call? Too often, they're greeted by an outdated phone system that sounds like it hasn't changed since the 1990s: "Thank you for calling... For Customer Service, press 1... For Billing, press 2... For Technical Support, press 3... For Sales, press 5..." After navigating the menu, they're rewarded with another message: "The person you are trying to reach is unavailable. Please leave your name and number. Someone will return your call." At that point, many prospects don't leave a voicemail. They call your competitor instead.
By Kirk Conole • July 29, 2026
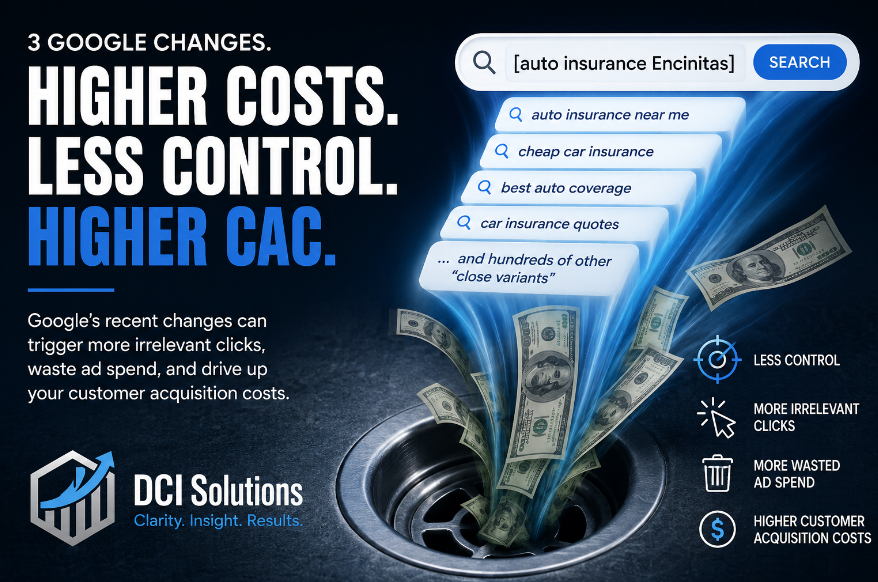
Google Ads has always evolved, but a few recent changes have made it more difficult for businesses to control where their advertising dollars go. Three changes, in particular, can have a direct impact on your customer acquisition costs (CAC): Expanded "exact match" keywords to include broader "close variants." Shifted more bidding decisions to AI-driven automation. Reduced transparency into how advertising prices are determined. At first glance, these updates may sound like improvements designed to increase reach and efficiency. In reality, they can also result in your ads appearing for searches you never intended to target. For example, you might bid on the exact-match keyword [auto insurance Encinitas] , expecting your ads to appear only for that specific search. Instead, Google may show your ad for broader searches it considers to be a "close variant." While some of those clicks may be valuable, others may come from users who are unlikely to become customers. The result is simple: More irrelevant clicks Higher advertising spend Lower campaign efficiency Increased customer acquisition costs Many businesses assume rising advertising costs are simply the new normal. In reality, a portion of that increase may be caused by how campaigns are configured and how Google's automated systems are making decisions on your behalf.  That doesn't necessarily mean you need to replace your marketing agency. It does mean it's worth taking a closer look at where your advertising dollars are going. At DCI Solutions , our independent advertising audit is designed to uncover wasted ad spend, identify hidden inefficiencies, and provide objective recommendations, all while allowing you to continue working with your current agency if you choose. Before increasing your advertising budget, make sure you're maximizing the one you already have.
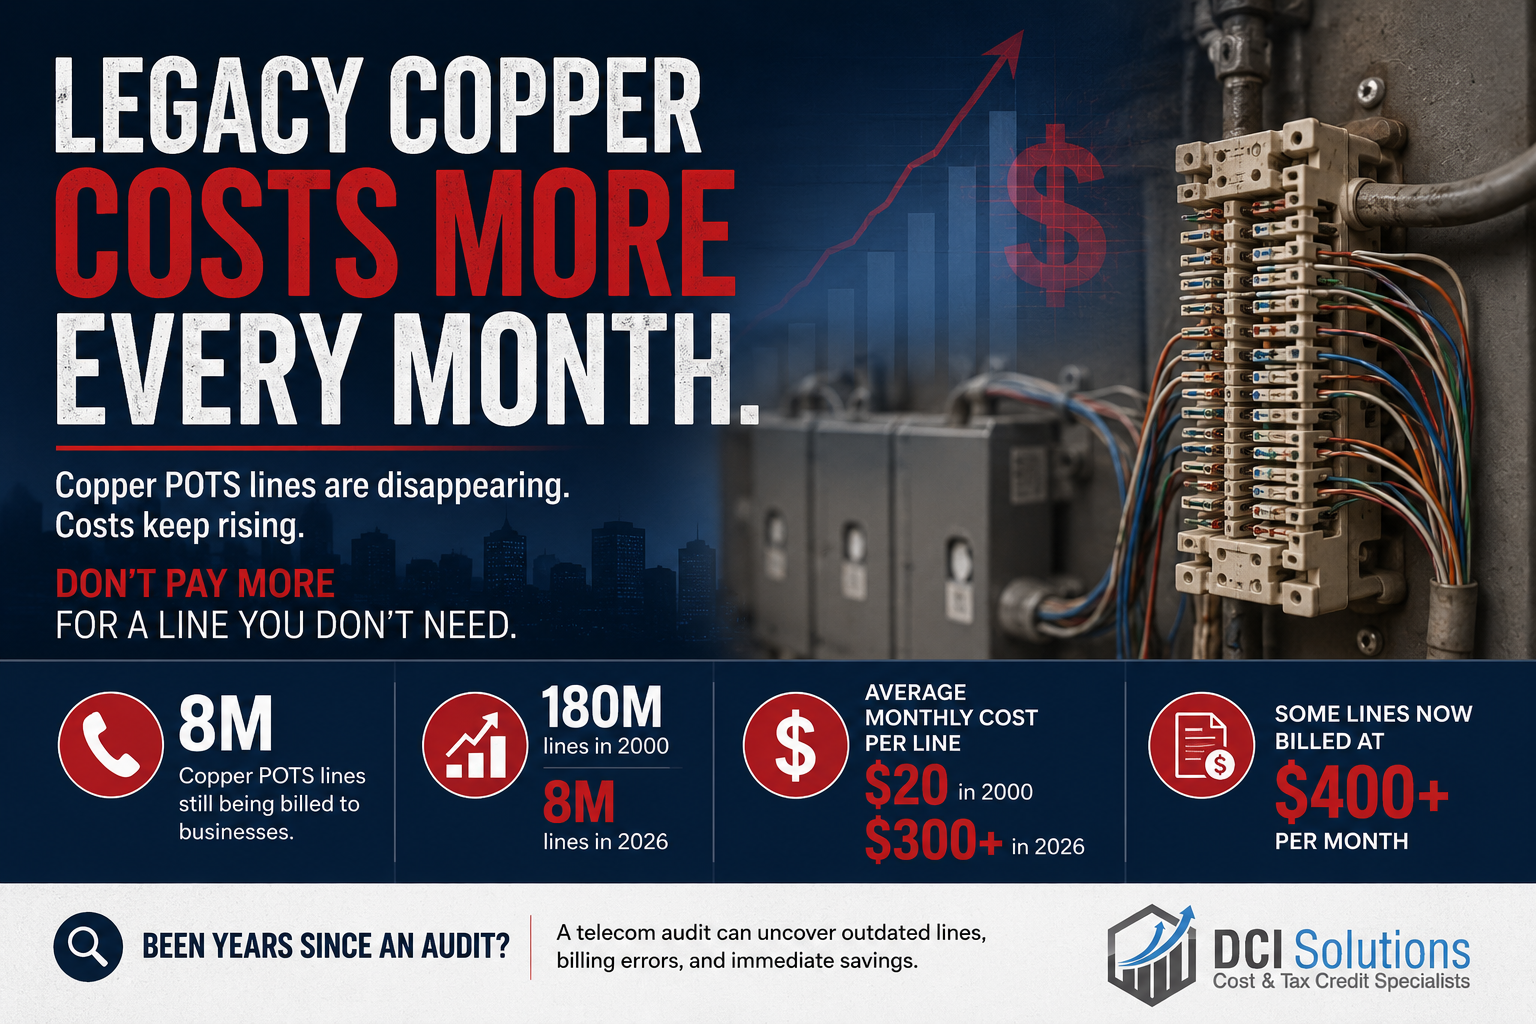
Blue ad: “Legacy copper costs more every month” with cable rack and cost icons from DCI Solutions.
By Kirk Conole • July 8, 2026
Legacy copper POTS lines are driving up telecom costs. Conduct audits to identify savings. Contact us for help!
Construction promo graphic: “Structuring beats shopping,” claiming $1 million saved on insurance premiums.
By Kirk Conole • June 23, 2026
Many construction firms assume the best way to lower insurance costs is to shop their coverage to as many carriers as possible. In reality, that approach often produces the same result: multiple quotes based on the same flawed assumptions, inflated values, and standard market pricing.  Recently, a builder reduced construction insurance premiums by more than $1 million without a traditional shopping exercise. The savings came from restructuring the program before it ever reached underwriting.
By Kirk Conole • June 19, 2026
For many IT leaders, it starts with what sounds like a routine phone call. Oracle reaches out requesting a "quick discussion" about your Java environment. The conversation is typically positioned as a support check-in, a licensing update, a security discussion, or a general review of your organization's Java usage. On the surface, it appears harmless. In reality, the discussion often serves a much different purpose: determining whether Oracle Java exists anywhere within your environment. Once that is established, the conversation tends to shift quickly. Questions may include: How many employees does your organization have? Who is using Oracle Java? Which systems rely on it? Are contractors or subsidiaries involved? How broadly is Java deployed across the enterprise?  At that point, the licensing exposure calculation begins.
Blue Collar Workers tax credit flyer with earnings examples and white text on a dark banner
By Kirk Conole • June 10, 2026
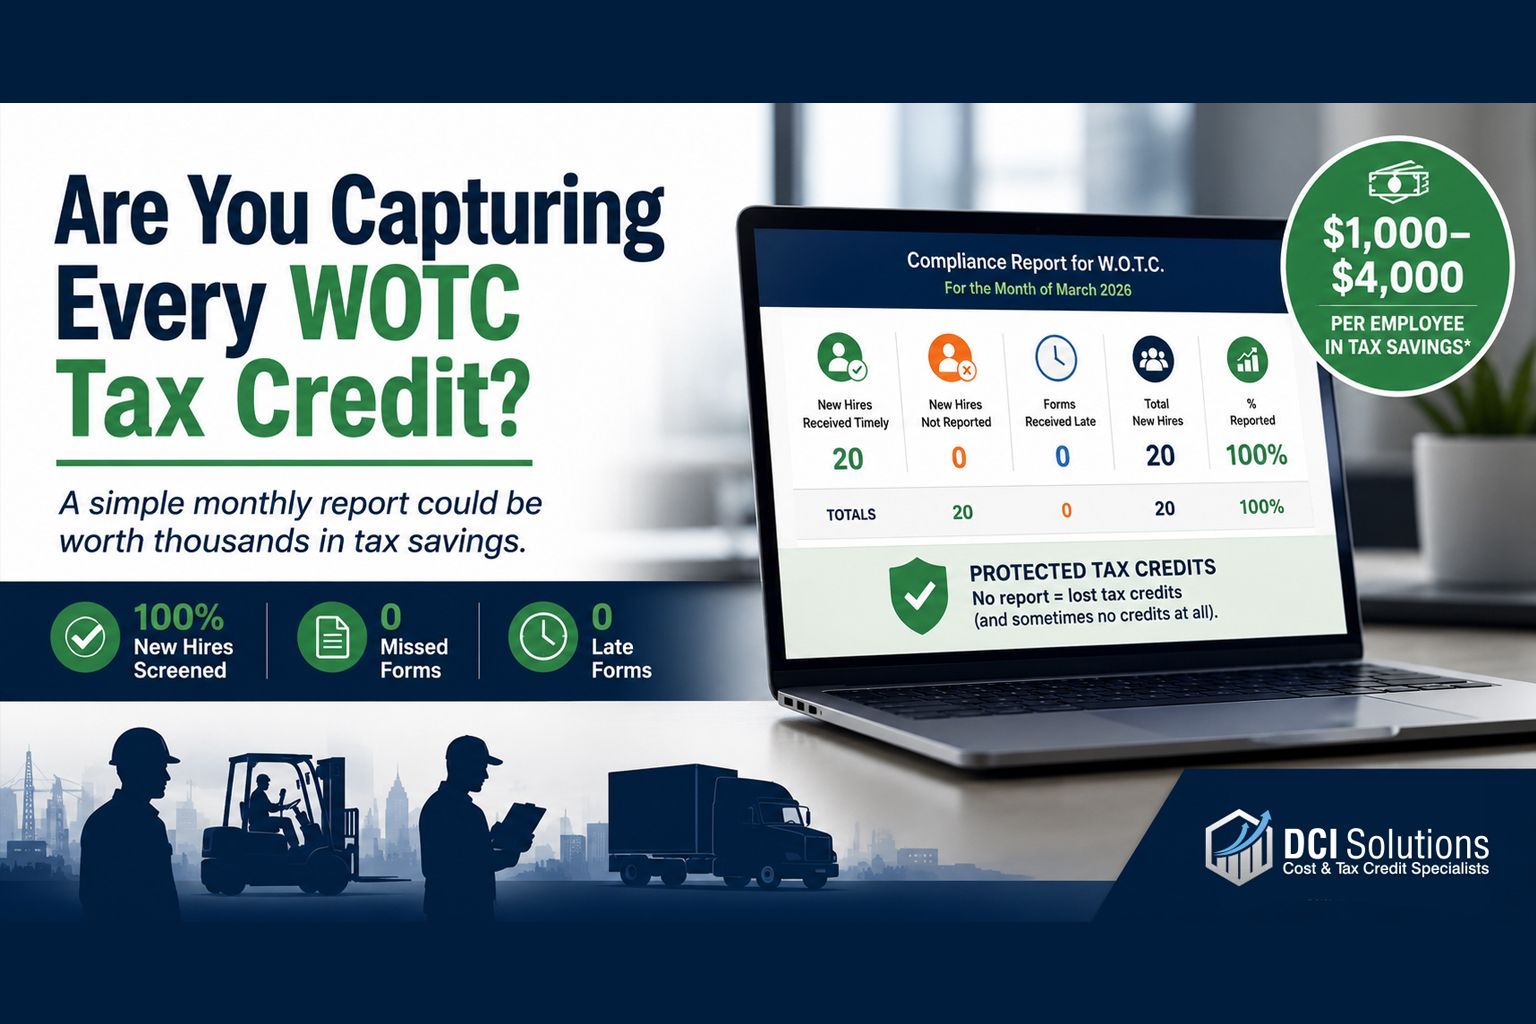
Many employers who hire blue-collar workers assume they're receiving every available Work Opportunity Tax Credit (WOTC). The reality is that many companies lose valuable tax credits simply because the process isn't being monitored correctly. One of the easiest ways to verify compliance is through a monthly reporting system. A simple report should clearly show: New hires screened on time Missed forms Late submissions Overall compliance percentage In the example below, the employer achieved: 100% of new hires screened on time 0 missed forms 0 late forms That level of compliance helps ensure tax credits are protected and available when it's time to file. The problem is that many organizations never receive this type of visibility. Without regular reporting, missed screenings and late paperwork can quietly eliminate tax credits that should have been captured. The financial impact can be significant. Even a relatively small number of qualified hires may generate thousands of dollars in tax savings. In many cases, companies discover additional opportunities through an independent audit of their tax credit and operational processes. A thorough forensic review often uncovers overlooked savings, compliance gaps, and process inefficiencies. For many organizations, the combined effect can translate into meaningful cash flow improvements without changing vendors, disrupting operations, or taking on additional risk. The question isn't whether WOTC credits exist for your workforce. The question is whether you're capturing every dollar you're entitled to. When was the last time an outside expert reviewed your process?  Being busy is understandable. Leaving money on the table isn't.
By Kirk Conole • June 4, 2026
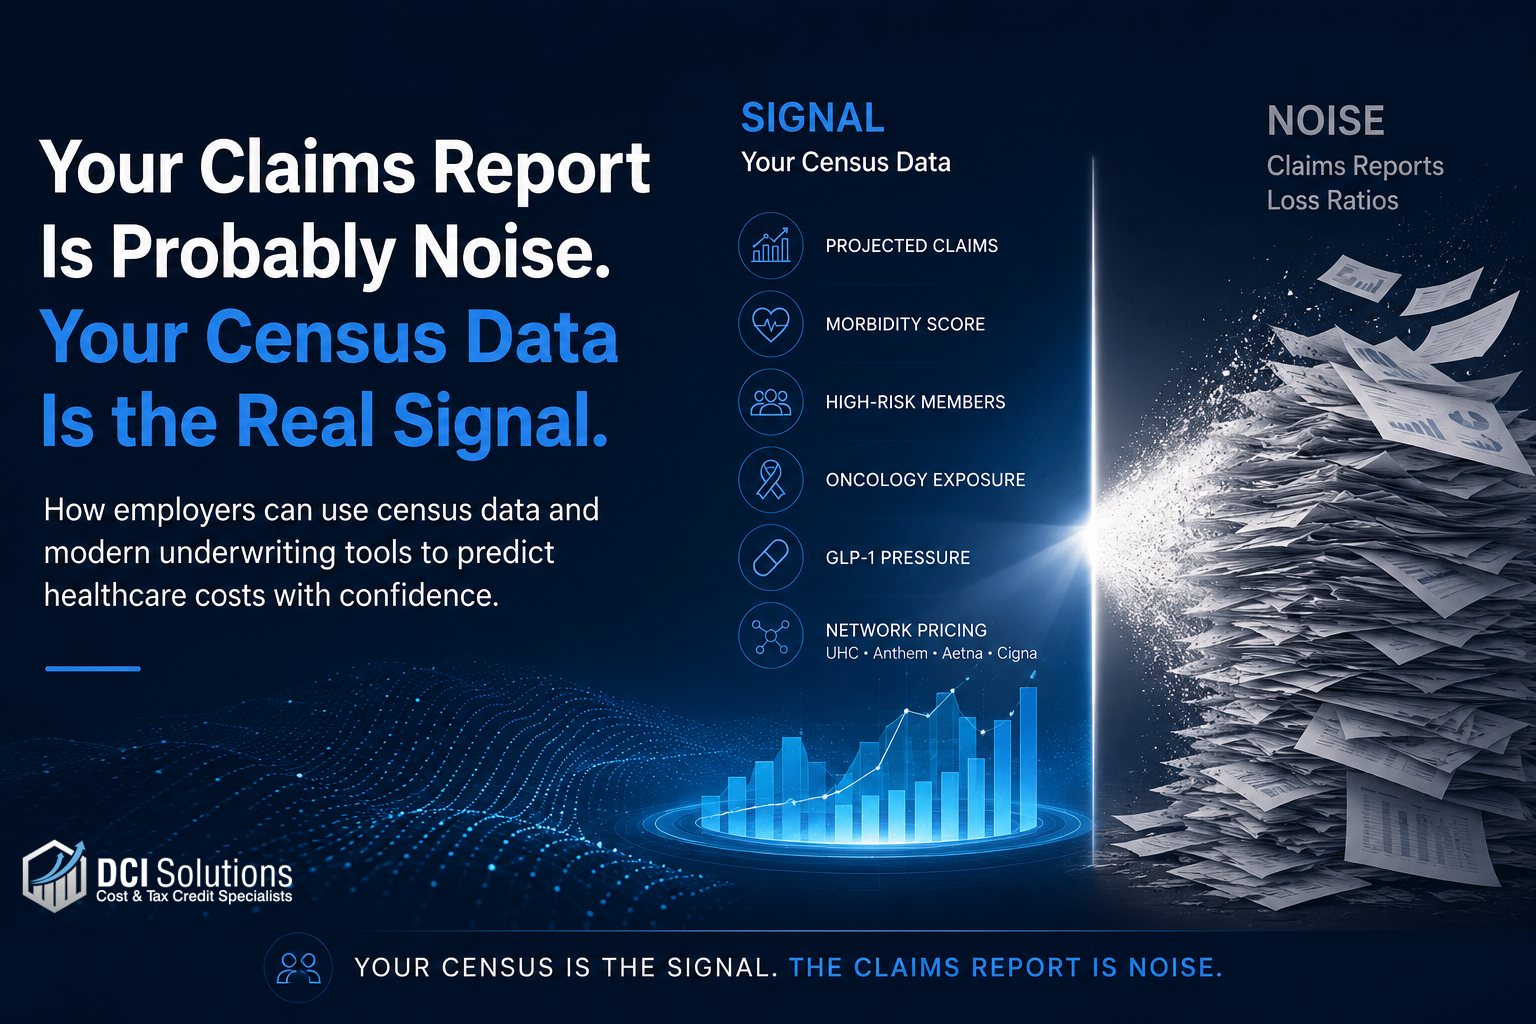
For decades, employers have been conditioned to believe that health insurance claims reports are the key to understanding healthcare costs. They're not. In fact, by the time most employers receive a claims report, the information is already historical. It tells you what happened, not what's likely to happen next.  That's a problem when healthcare spending continues to rise and employers are being asked to make critical decisions about funding strategies, stop-loss coverage, network selection, and employee benefits.